Netflix needs content it can own forever.
Not just hit shows that spike for a quarter.
Not just binge-worthy originals that fade after a season.
It needs franchises.
Libraries.
Intellectual property with decades of cultural gravity.
That’s the real endgame of the streaming wars.
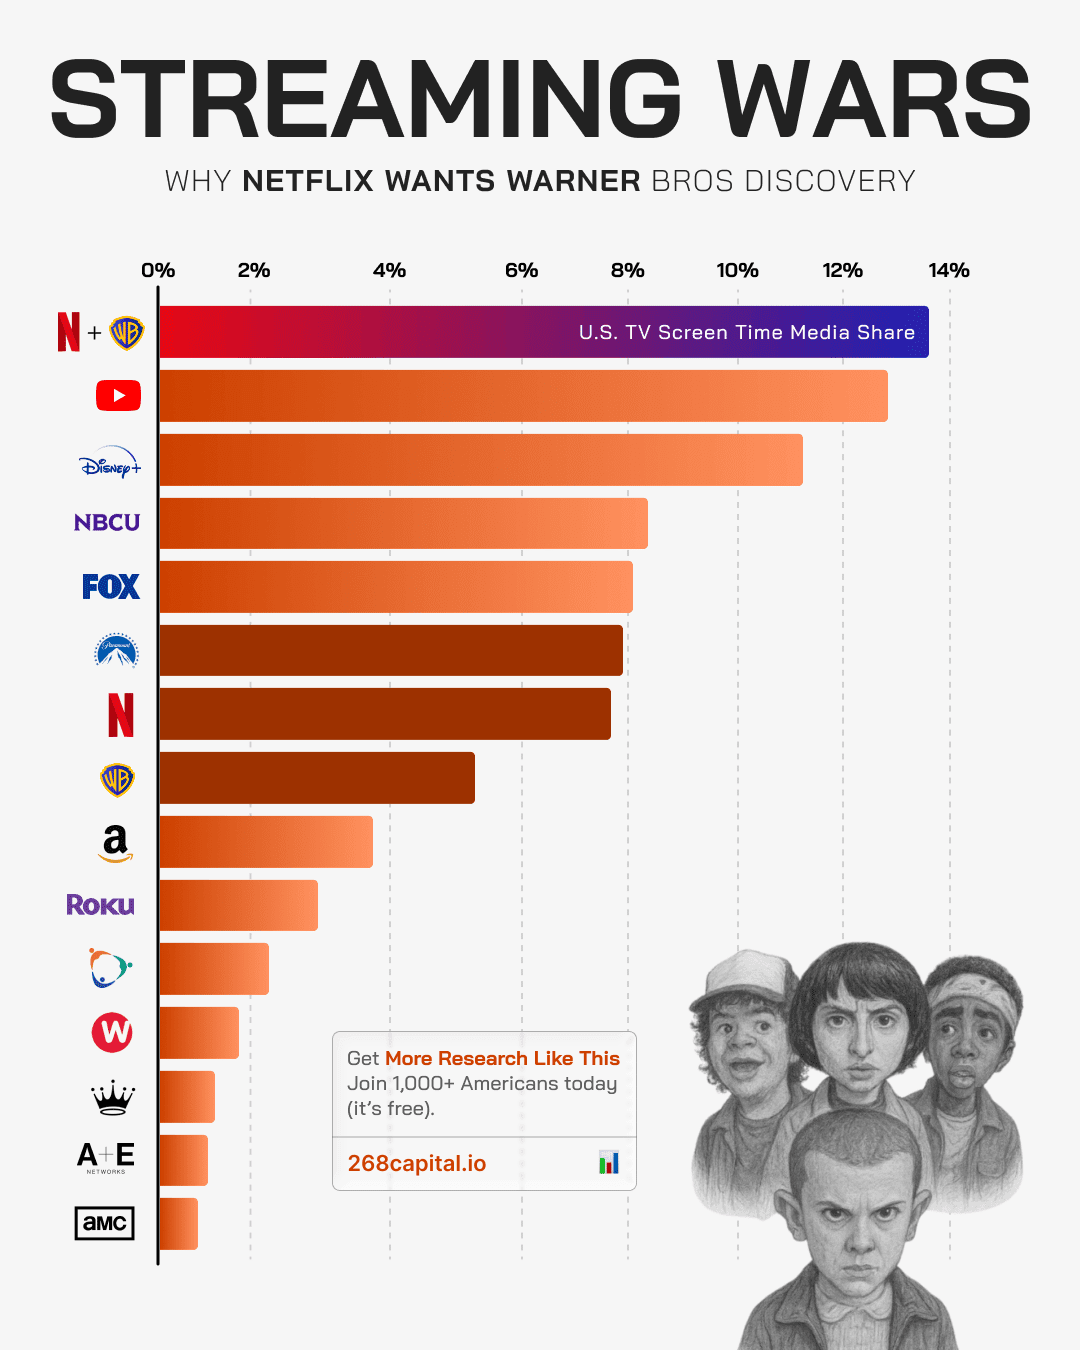
And that’s exactly why Warner Bros. Discovery is suddenly the most important asset in Hollywood.
Want More Free Stock Market Research? Click Here.
The Problem Warner Bros. Is Facing
Warner Bros. Discovery didn’t put itself up for sale because management woke up one day and wanted to exit.
It was forced there.
In 2022, AT&T offloaded WarnerMedia to clean up its balance sheet and refocus on telecom. Discovery took the deal — and the debt — creating a media giant with massive scale and massive leverage.
Roughly $40 billion in debt came along for the ride.
At the time, the logic made sense:
-
Streaming would keep growing
-
Cable would decline slowly
-
Synergies would stabilize cash flow
None of that played out as planned.
Cable TV revenues collapsed faster than anyone modeled.
Advertising softened.
Streaming losses at HBO Max and Discovery+ ballooned.
For three straight years, Warner Bros. Discovery burned cash while servicing one of the heaviest debt loads in media.
By late 2025, reality set in.
This wasn’t a turnaround story anymore.
It was a balance-sheet problem.
Warner needed a buyer with the financial strength to stop the bleeding — and the patience to let its assets compound over time.
Netflix’s Hidden Weakness
On the surface, Netflix looks untouchable.
It dominates global distribution.
It owns the subscriber relationship.
It has unmatched data on viewing behavior.
But beneath that dominance is a structural weakness.
Netflix does not dominate franchises.
Disney owns Marvel, Star Wars, Pixar, and Disney Animation.
Universal owns Jurassic Park, Fast & Furious, Minions.
Warner owns Harry Potter, DC, Lord of the Rings, and HBO’s entire prestige catalog.
Netflix, by contrast:
-
Produces hits, but very few timeless, multi-decade IPs
-
Must constantly spend to refresh its library
-
Relies on content velocity rather than content ownership
-
Faces slowing subscriber growth in most developed markets
As the streaming market matures, this matters more every year.
In a high-growth world, volume wins.
In a slower-growth world, libraries win.
And that’s the gap Netflix can’t fix organically.
Why Warner Bros. Solves That Problem
Acquiring Warner Bros. Discovery would instantly change Netflix’s DNA.
It wouldn’t just be a streaming platform anymore.
It would become a vertically integrated entertainment empire.
The deal would give Netflix:
-
A century-deep content library
-
Global franchises with built-in audiences
-
Prestige IP (HBO) and mass-market IP (DC, Harry Potter)
-
Assets that monetize across streaming, theatrical, licensing, games, and merchandise
Most importantly, it shifts Netflix from renting attention to owning cultural real estate.
That’s why analysts keep coming back to the same conclusion:
In a slower-growth streaming world, owning IP beats funding originals — every time.
Why Paramount–Skydance Is Also Bidding
Paramount’s interest in Warner Bros. comes from a very different place.
Netflix wants transformation.
Paramount wants survival.
Cable is still central to Paramount’s ecosystem.
Advertising, sports rights, and affiliate fees remain critical to its cash flow.
Adding Warner’s networks strengthens that position:
-
More leverage with advertisers
-
More negotiating power with distributors
-
Greater political and media influence (CNN alone matters here)
Scale buys time.
But it doesn’t eliminate the risk.
Cable decline doesn’t stop just because you’re bigger.
If anything, losses can scale right along with revenue.
Paramount’s bid is about consolidation and defense — not long-term reinvention.
The Strategic Fork in the Road
This deal represents two very different bets on the future of entertainment.
Netflix’s bet:
IP ownership + global distribution = long-term dominance
Paramount’s bet:
Scale + cable + advertising = survival through consolidation
Warner’s goal:
Find a buyer that stabilizes finances without stripping the crown jewels
Netflix currently looks like the frontrunner. But the risks are real:
-
Legacy studio culture colliding with Netflix’s speed-first model
-
Union, guild, and theatrical norms
-
Regulatory scrutiny (lower than Big Tech, but still present)
This isn’t an easy integration.
But strategically, it’s hard to ignore.
The Bigger Picture
This isn’t just a merger story.
It’s a signal.
Streaming growth is slowing.
Original-content arms races are losing efficiency.
And ownership of franchises is becoming the real moat again.
The winner of this deal won’t just control more content.
They’ll influence:
-
How entertainment is financed
-
How IP is developed and protected
-
How pricing power returns to the industry
Whoever wins reshapes Hollywood — not for a cycle, but for decades.
And that’s why this deal matters far more than the headlines suggest.
Want More Free Stock Market Research? Click The Button Below.